The Inside Story Behind Rising Diesel Prices
By James and Michael Hall
James and Michael Hall—authors of the popular The Sword of Damocles: Our Nuclear Age, now on Audible, Kindle and Amazon books. jameshall042999@gmail.com
The current energy crisis is not so much about a shortage of oil—it is a refining problem. It is a US refining problem.
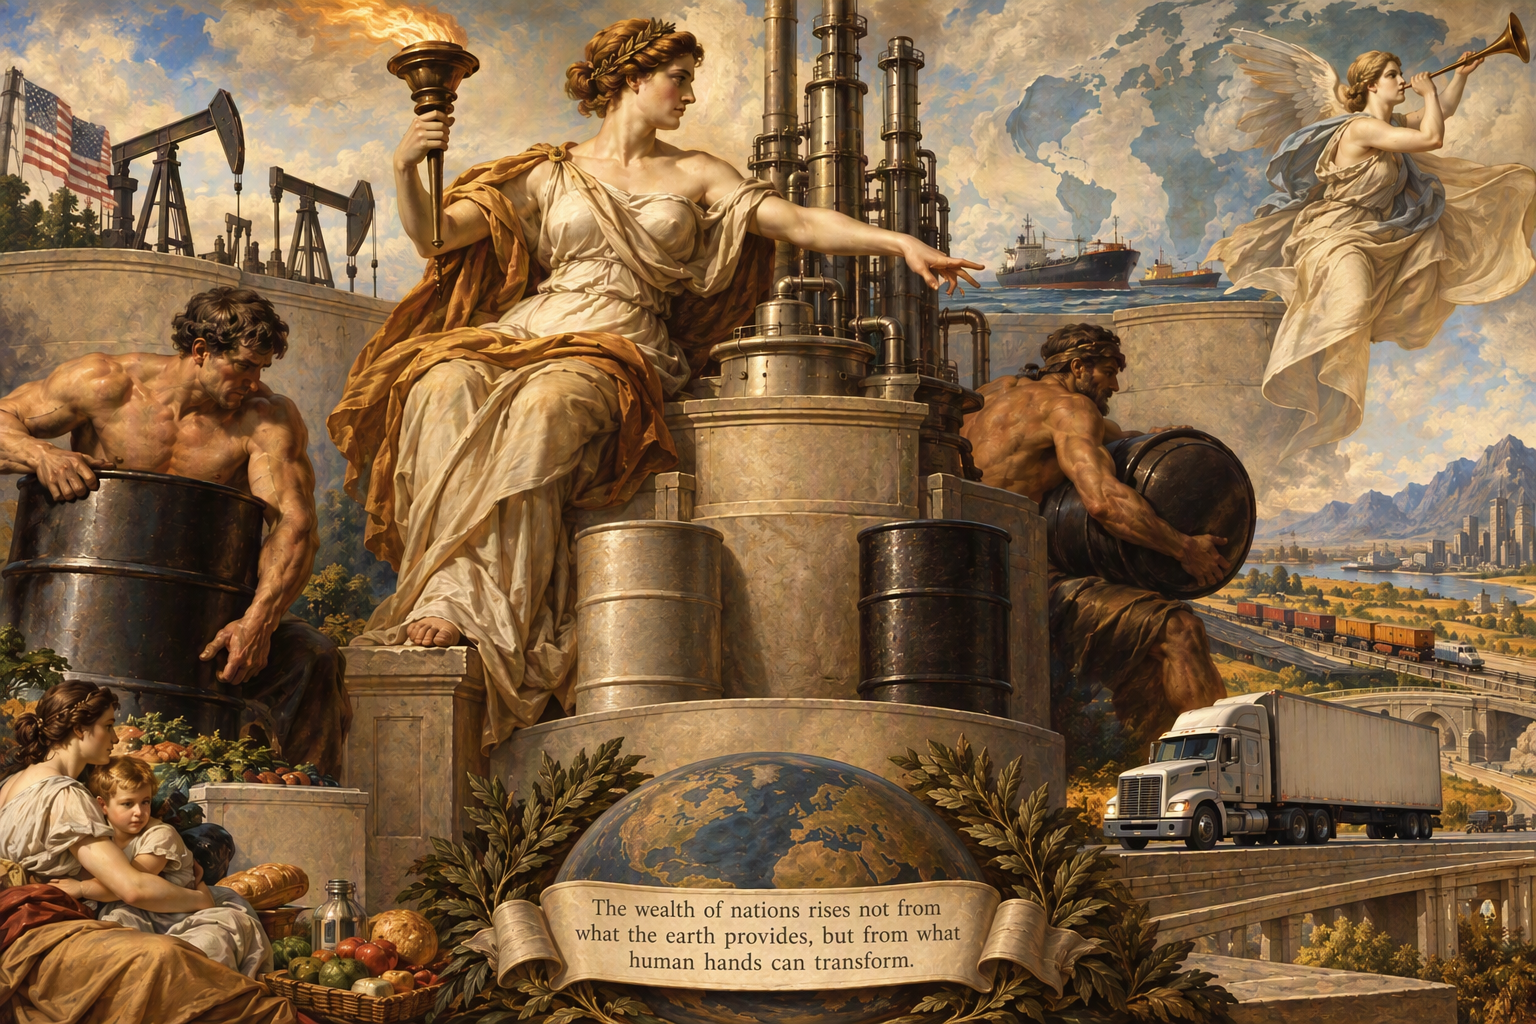
The wealth of nations rises not from what the earth provides, but from what human hands can transform.
Art and poetry by James Hall
The Energy Problem Isn't Just About Oil Supply
The United States is producing near-record amounts of crude oil, much of it from fracking. The catch? Most of that oil is light, sweet crude.
For decades, however, US refineries—especially along the Gulf Coast—invested billions in cokers, hydrocrackers, and desulfurization units built to process heavier, higher-sulfur crude imported from countries like Canada, Mexico, and Venezuela. Those grades are cheaper to buy, and the equipment is designed to upgrade the heavy, low-value "bottom of the barrel" into diesel, jet fuel, and gasoline. That conversion is where the profit lies.
Light shale oil doesn't fit that model. It yields a large share of light products such as naphtha and gasoline components, leaving expensive upgrading units underused. Run too much of it, and a complex refinery is effectively paying for equipment it isn't using.
That mismatch creates a strange reality: America exports large volumes of its own light crude while continuing to import heavier crude that better fits its refineries' design and economics. Refineries can process a range of oils, but they are most profitable and efficient when running the blends they were built to handle.
The problem isn't that America lacks oil. The problem is that much of our energy infrastructure wasn't built for the oil we're producing today.
This structural disconnect is compounded by geography and domestic shipping policy. Most of the East Coast's diesel arrives from Gulf Coast refineries through the Colonial Pipeline, which runs from Houston to New York Harbor and often operates at or near capacity. When the pipeline is full, the next option is by sea, and that is where the century-old Jones Act comes in. Under the law, any cargo moved between two US ports must travel on vessels that are US-built, US-flagged, and largely US-owned and crewed.
Because Jones Act-compliant tankers are few and costly to charter, Gulf Coast refiners often find it cheaper to send diesel across the Atlantic to Europe or Latin America than up the coast to Boston or New York. New England, which lies beyond the pipeline's reach, relies heavily on waterborne deliveries and imports from Canada and Europe for its heating oil and diesel. As a result, East Coast consumers are exposed to international freight shocks, foreign bidding wars, and global supply squeezes, even while domestic refineries run near capacity.
Some argue the solution is to restrict diesel exports and keep more fuel at home. That may sound logical, but it ignores how the global energy market actually works. The United States depends on international trade for both crude oil and refined products, and parts of the country already rely on imported fuel. Restricting diesel exports would disrupt those trade flows, invite retaliation from trading partners, and do little to fix the underlying refinery mismatch that is driving shortages and higher prices.
(Note: Most major US refineries were originally built between the 1940s and 1970s. The last large refinery built from the ground up, Marathon's Garyville plant in Louisiana, opened in 1977. Since then, companies have expanded, upgraded, and modernized existing facilities rather than building new ones. The number of operable US refineries has fallen from 301 in 1982 to about 130 today, yet total capacity has held up because the surviving plants grew larger and more complex. That cushion is now thinning: US refining capacity declined in 2025, and closures in Houston and California have taken more plants offline since.)
Why Diesel Is Often Hit Harder
Diesel is often the first fuel to feel the pain when energy markets tighten.
That's because diesel, jet fuel, and heating oil all belong to a group called middle distillates, and they are produced more efficiently from medium and heavy crude oils than from the light crude that dominates US production today.
As a result, America exports much of its light crude and imports heavier grades that are better suited for producing the diesel, jet fuel, and gasoline that keep the economy moving.
When refining capacity gets squeezed, diesel is usually the first pressure point. Demand remains relentless. Trucks need it. Farmers need it. Construction equipment runs on it. Ships use it. Industry depends on it. There is no easy substitute.
Several forces are now converging on the global diesel market:
Refining capacity is running near its limits. Many refineries in the United States and around the world are already operating at very high utilization rates, leaving little room to absorb unexpected outages or spikes in demand.
Russian diesel exports have been disrupted. Sanctions, export restrictions, and repeated attacks on refining infrastructure have reduced supplies from one of the world's most important diesel-producing regions.
Middle East instability threatens critical energy corridors. Attacks on energy infrastructure and growing regional tensions create risks for production, refining, storage, and shipping networks that supply fuel to global markets.
Europe remains vulnerable, prompting calls for coordinated action. After losing traditional access to Russian barrels, Europe became reliant on imports from the Middle East, Asia, and the United States. With Middle East corridors under pressure, Washington and European capitals are increasingly urged to coordinate commercial stock draws, harmonize export policies, and manage maritime freight routes together rather than competing for the same marginal cargoes.
US refiners cannot bear the burden alone. American refiners are caught balancing domestic fuel security against export commitments to key European allies. Without formal bilateral coordination to manage inventory flows and refining utilization, sudden policy moves—like export curbs—risk triggering acute price spikes across both economies.
A tightening global tanker shortage magnifies every transit shock. Even when crude is extracted and refineries produce fuel, oil cannot relieve market pressure without the physical ships available to move it. Years of underinvestment in new vessel construction, shipyard backlogs, and the siphoning of hundreds of aging hulls into an opaque, sanctioned "shadow fleet" have left the compliant commercial tanker pool dangerously stretched. When conflict forces ships to bypass key choke points like the Red Sea or Hormuz to sail around Africa, voyage times increase by weeks. This surge in "ton-mile" demand ties up available capacity, effectively shrinking the world's functional shipping fleet overnight. The result is a brittle distribution chain where a localized maritime disruption quickly cascades into a worldwide shortage of delivered diesel.
The result is a system with almost no cushion. When a refinery goes offline, a shipping route is disrupted, or geopolitical tensions flare, diesel prices can spike rapidly because there is very little spare capacity available to fill the gap.
The key takeaway is that diesel is not priced by local supply alone. It is part of a tightly connected global market. What happens in Russia, the Middle East, Europe, or Asia can affect the price paid by a truck driver, farmer, or business owner in the United States almost overnight.
The Illusion of Reserve Numbers and the Supply Fog
One of the most persistent misconceptions during an energy crisis is that reserve numbers tell the entire story. They do not.
Much of the public discussion focuses on crude oil inventories while overlooking the fuels that actually power modern economies. Strategic reserves may appear reassuring on paper, but crude oil is only the raw input. Until it is refined into diesel, gasoline, jet fuel, and other products, it cannot be used by most consumers or businesses.
When governments tap strategic petroleum reserves, they release crude oil, not finished fuels. Those barrels must still move through refineries before they become usable products. If refining capacity is constrained, additional crude does little to alleviate immediate shortages.
The critical question is not,"How much oil do we have?" The more important question is,"How many days of usable fuel do we have?"
That answer is becoming increasingly difficult to determine.
Reliance on emergency crude releases is a strategy with diminishing returns. Before the latest Middle East supply disruptions, the US Strategic Petroleum Reserve (SPR) held approximately 382 million barrels of crude. By June, inventories had fallen below 311 million barrels, and by late September 2026 the reserve stood at roughly 283.8 million barrels, its lowest level since October 1982 and less than 40% of its authorized 714 million-barrel storage capacity.
This trend raises a broader policy question. The SPR was established under the Energy Policy and Conservation Act of 1975 as a strategic safeguard against severe physical supply disruptions and national emergencies. While reserve releases can provide temporary market relief, sustained drawdowns inevitably reduce the margin of protection available during future crises.
At the same time, visibility into global fuel availability remains imperfect. Commercial inventories are often reported with delays, cargoes are routinely redirected, and stockpiles are being accumulated in some regions while depleted in others. The result is an increasingly opaque picture of global diesel and gasoline supplies.
This creates a dangerous gap between paper supply and real-world availability. A barrel of crude stored underground is not equivalent to diesel in a truck stop tank or gasoline ready for retail distribution.
Signs of strain are already emerging across parts of the global energy market. Regional shortages, logistical disruptions, and tightening fuel inventories suggest that the buffer protecting consumers may be considerably thinner than headline reserve figures imply.
Reserve statistics can therefore create an illusion of security. What ultimately matters is not the volume of crude oil recorded on balance sheets, but the amount of finished fuel that can reach consumers when they need it. In an energy crunch, crude oil is potential. Diesel and gasoline are reality.
How Higher Diesel Prices Affect Everyone
Diesel is the fuel that keeps the US and world economy moving. It powers farm equipment, freight trains, cargo ships, construction equipment, and the trucks that deliver products to stores.
Diesel touches everything we consume—often as much as six times before products reach the shelves.
Because diesel is involved at multiple stages of production and transportation, higher diesel prices tend to push up the cost of many everyday goods. Food, building materials, consumer products, and industrial supplies all become more expensive to move and distribute.
This is why energy markets are not just about how much oil is produced. They are also about whether the right refining capacity exists in the right locations to convert the right crude oil into the fuels people and businesses need.
How Bad Could It Get?
If several existing vulnerabilities were to occur at the same time, the economic impact could be significant.
1. Higher Inflation and Slower Growth.
Because diesel is a key input cost across the economy, a sustained price spike can increase inflation while also weighing on economic growth. This combination is sometimes called stagflation.
2. Pressure on Agriculture and Food Prices.
Modern farming depends heavily on diesel-powered machinery and transportation. Higher fuel costs increase production expenses and can contribute to higher food prices.
3. Supply Chain Disruptions.
Freight transportation cannot easily stop when fuel becomes expensive. Severe diesel shortages could force shipping companies to prioritize critical goods such as food, medicine, and energy supplies while delaying less essential cargo.
4. Export Restrictions and Fuel Hoarding.
Compounding these logistical bottlenecks is a sudden supply contraction from the Pacific: China has moved to halt refined fuel exports—most critically diesel—heading into the final quarter. After surging export volumes in late summer left domestic commercial diesel stockpiles depleted to decade-low levels, Beijing abruptly ordered state and private refiners to curb overseas shipments to safeguard internal agricultural and industrial demand. By cutting off its export taps precisely when Russian barrels remain sidelined by sanctions and attacks, China removes another vital marginal supplier from the global board. The move leaves European and Asian importers bidding over an increasingly narrow pool of seaborne distillates, transferring immediate upward price pressure directly onto Western markets.
The Crisis is only getting worse
Over the past month, the Middle East has felt less like a region experiencing isolated incidents and more like one drifting into total chaos. Headlines have focused on individual tanker attacks, missile launches, and strikes on oil facilities, but together they tell a larger story. The confrontation has increasingly shifted away from traditional military targets and toward the arteries of the global energy system. Tankers, export terminals, pipelines, pumping stations, and refineries have become strategic objectives, not because any single strike can halt oil flows, but because repeated attacks create uncertainty, fear, and rising costs.
The first signs of the latest escalation emerged in the Strait of Hormuz. Several tankers reported being struck by projectiles while leaving the Gulf, including two supertankers carrying Saudi crude. The attacks occurred within minutes of one another, sending an unmistakable signal to shipping companies and energy markets that transit through Hormuz could no longer be taken for granted. Although the vessels survived and continued their voyages, the psychological impact was immediate. Insurance premiums rose, security warnings multiplied, and operators began reassessing the risks of entering the region.
As tensions mounted at sea, attention shifted to Saudi Arabia's energy infrastructure. Recent attacks and attempted attacks on Saudi Aramco facilities in Yanbu and Jazan suggested that the conflict was expanding beyond merchant shipping. These sites are strategically significant because they support Saudi Arabia's growing reliance on Red Sea export routes as an alternative to Hormuz. By targeting infrastructure linked to those routes, attackers appeared to be challenging not only Saudi production capacity but also the Kingdom's ability to circumvent maritime disruptions in the Gulf.
In many respects, this represented a continuation of a strategy first demonstrated in the attack on pumping stations along Saudi Arabia's East-West Pipeline. The significance of that strike lay less in the physical damage than in what it revealed. The pipeline was built to reduce dependence on the Strait of Hormuz by linking eastern oil fields to the Red Sea port of Yanbu. Yet the attack highlighted a critical reality: alternative export routes can themselves become targets. Diversification may reduce exposure to a single chokepoint, but it does not eliminate vulnerability.
The situation intensified further as reports emerged of direct actions against tankers by both sides of the broader conflict. US forces reportedly struck Iranian-linked vessels, while Iran claimed retaliatory actions against multiple tankers near Hormuz. Whether every claim can be independently verified is ultimately less important than the broader trend. Commercial shipping has increasingly become part of the battlefield. Energy markets responded quickly, with oil prices rising as traders priced in the possibility of sustained transportation disruptions rather than simple production losses.
By the middle and latter part of September, additional reports of projectile strikes, vessel fires, and crew injuries reinforced the sense that these were no longer isolated incidents. Multiple tankers were damaged within a relatively short period of time. Some attacks were attributed to known actors, while others remain unexplained. The cumulative effect has been profound. Shipping companies, insurers, commodity traders, and governments are no longer reacting to individual events. They are responding to a pattern.
The vulnerability is no longer confined to commercial shipping; it now extends to the military architecture designed to protect it. The US naval installation in Bahrain was never simply a base. As headquarters of the US Fifth Fleet, it served as the command center and logistical backbone of American maritime power across the Persian Gulf, Red Sea, and Gulf of Oman. For decades, it functioned as the primary hub for fleet sustainment, maintenance, and regional operations.
If reports of recent Iranian strikes are accurate, the damage extended beyond physical infrastructure. The reported degradation of warehouses, supply depots, and logistical support networks appears to have impaired the base's ability to sustain forward operations, forcing critical support functions to shift thousands of miles south to Diego Garcia.
That relocation has significant operational consequences. Longer supply lines increase turnaround times for munitions, repairs, and routine provisions while adding friction to sustained naval operations. More importantly, it exposes a deeper vulnerability: the logic of forward-projected power begins to weaken when the sanctuary supporting it can no longer be assumed secure.
With naval protection operating under greater strain, commercial shipping has increasingly been left to adapt on its own. One of the clearest indicators of rising risk has been tanker behavior itself. Operators have reportedly begun switching off AIS tracking systems while transiting high-risk waters, reducing the public visibility of vessel movements. Oil continues to flow, but it does so in a more cautious, opaque, and unpredictable environment.
Taken together, these developments increasingly resemble a new model of economic warfare. The repeated drone strikes on Russian refineries, the attacks on Saudi pumping stations, the harassment of commercial tankers in Hormuz, and the targeting of export infrastructure throughout the region all reflect a common strategic logic. Rather than seeking decisive battlefield victories, states and non-state actors are attempting to impose costs, disrupt logistics, create uncertainty, and shape political decision-making through pressure on energy systems.
The events of recent weeks are therefore best understood not as a series of disconnected incidents, but as part of an emerging contest over the world's energy lifelines, where disruption itself has become a strategic objective.
The significance of this shift extends far beyond the Middle East. Russia's recent warnings regarding Kaliningrad reflect a similar strategic logic. Whether the issue is tanker traffic through Hormuz, pumping stations along the Saudi East-West Pipeline, Ukrainian strikes on Russian refineries, or access to Moscow's Baltic enclave, modern geopolitical competition is increasingly centered on critical nodes of transit, logistics, and energy. The contest is no longer simply over territory. It is increasingly about the infrastructure that allows states to project power, sustain their economies, and preserve strategic freedom of action.
(This narrative was synthesized from reporting by Reuters, Lloyd's List, Maritime News, Gulf News, OilPrice.com, Saudi Press, US News & World Report, and other cited sources published between August and October 2026.)
Bottom Line
Before the war, roughly 20 million barrels of oil and petroleum liquids moved through the Strait of Hormuz each day. At the peak of the disruption, flows fell to approximately 6 million barrels per day, or about one-third of normal levels. While crude shipments have since recovered substantially through alternative routes and military-protected transit corridors, refined fuel supplies remain significantly more constrained.
The key challenge is not simply the amount of oil being produced. It is whether the global refining system can efficiently turn that oil into the fuels the economy depends on, especially diesel.
Refining constraints, aging infrastructure, geopolitical disruptions, and strong worldwide demand can all tighten diesel markets. While catastrophic shortages are not inevitable, continued underinvestment in refining capacity and fuel infrastructure could keep diesel prices elevated and leave the global economy more vulnerable to future disruptions. We may be in for a terrible crisis.
The growing bond and rising yield crisis is intimately tied to the surge in diesel prices. Diesel shocks act as an accelerant for the bond sell-off, while rising yields raise the cost of capital across the supply chain, locking high energy prices into the real economy.
This seems to be a mystery to many. People view rising diesel prices and rising bond yields as separate stories. In reality, they are part of the same cycle.
When diesel prices surge, the cost of moving goods, operating equipment, and producing essential products rises with them. That inflationary pressure ripples throughout the economy, forcing investors to demand higher yields on bonds as compensation for rising costs and increased uncertainty.
But the feedback loop does not stop there.
As bond yields rise, borrowing becomes more expensive. Energy companies, refiners, trucking fleets, farmers, manufacturers, and infrastructure operators all face higher financing costs. Expanding refining capacity, upgrading equipment, or investing in new energy infrastructure becomes more difficult and more expensive.
The result is a vicious cycle:
Tight fuel supplies push diesel prices higher.
Higher diesel prices fuel inflation.
Inflation drives bond yields higher.
Higher yields raise the cost of investment and expansion.
Limited investment keeps fuel supplies tight.
The cycle then starts again.
Bibliography
Al Bawaba News. “Two Tankers Hit By Projectiles In Strait Of Hormuz, Two Crew Injured.” Eurasia Review, September 21, 2026. [eurasiareview.com]
Baystreet.ca. “Middle East Oil Exports Stage a Remarkable Comeback.” October 2, 2026. [baystreet.ca]
Bloomberg. “Houthis Attack Saudi Arabia, Claim to Target Aramco Facilities.” Energy Connects, September 24, 2026. [energyconnects.com]
DeepDraft Desk. “DeepDraft Weekly Maritime Brief: Hormuz Tanker Strikes, AIS Silence and Maritime Security Pressure.” The DeepDraft, September 6, 2026. [thedeepdraft.com]
Hilotin, Jay. “Oil Nears $100 as US Destroys Five Iranian Tankers, Iran Strikes Jordan and Hormuz Tensions Threaten Global Supply.” Gulf News, September 9, 2026. [gulfnews.com]
Karmactive. “Iran Claims 8 Tankers Hit in Hormuz as Ships Go Dark, Oil Flow Intact, Insurance Costs Rising.” September 18, 2026. [karmactive.com]
Lloyd’s List. “The Week in Charts: Iran’s Ship Attacks Show Strategy of Disruption Not Discrimination.” September 28, 2026. [lloydslist.com]
Maritime News. “Strait of Hormuz: Tanker Incidents and Depressed Flows Alter the Path of Hormuz Transits.” September 20, 2026. [maritimenews.com]
Maritime News. “Tanker Strikes and Blockade Drive New Hormuz Shipping Disruptions.” September 7, 2026. [maritimenews.com]
Moneycontrol. “Hormuz Ship Traffic Down 96%, Bab el-Mandeb at 70% of Normal Levels.” September 24, 2026. [moneycontrol.com]
OilPrice.com. “Global Shipping Costs Explode as Hormuz Disruptions Hit Key Trade Routes.” September 18, 2026. [oilprice.com]
Reuters. “Iran and US Hit Tankers in Biggest Wave of Attacks on Shipping Since War Began.” September 9, 2026. [reuters.com]
Reuters. “Two Tankers Carrying Saudi Oil Attacked in Strait of Hormuz.” September 1, 2026. [reuters.com]
Reuters. “Houthis Say They Attacked Riyadh and Aramco Facilities in Yanbu.” U.S. News & World Report, September 24, 2026. [usnews.com]
Saudi Arabia Reports Drone Strike on Key Red Sea Refinery in Yanbu. Saudi Press, October 2, 2026. [saudipress.com]
Saudi Aramco-Exxon Refinery in Yanbu Targeted in Latest Wave of Iranian Attacks. Saudi Press, October 2, 2026. [saudipress.com]
Financial Times: Aramco Facilities in Jizan Hit by New Attacks. Al-Khabar Al-Yemeni, September 8, 2026. [alkhabaralyemeni.net]
Houthis Strike Saudi Aramco's Jazan Refinery by Drone as Iran Hardens Hormuz Demands. Political.org, August 9, 2026. [political.org]
Notes:
Russia's recent warnings about Kaliningrad are interesting because they do not appear to be a response to any immediate threat. Neither NATO nor the European countries bordering Kaliningrad are currently threatening to attack or seize it. Yet Moscow has suddenly elevated the issue, first through diplomats and officials, and then through Vladimir Putin himself, who publicly stated that Russia would use all means available, including nuclear weapons, to defend Kaliningrad if it were attacked.
What makes Putin's involvement significant is that he usually leaves such warnings to subordinates. When he repeats them personally, it often means the Kremlin wants foreign governments to take the message seriously.
The puzzle is that no one is talking about attacking Kaliningrad today. So what is Russia worried about? What are they up to?
James and Michael Hall—authors of the popular The Sword of Damocles: Our Nuclear Age, now on Audible, Kindle and Amazon books.